
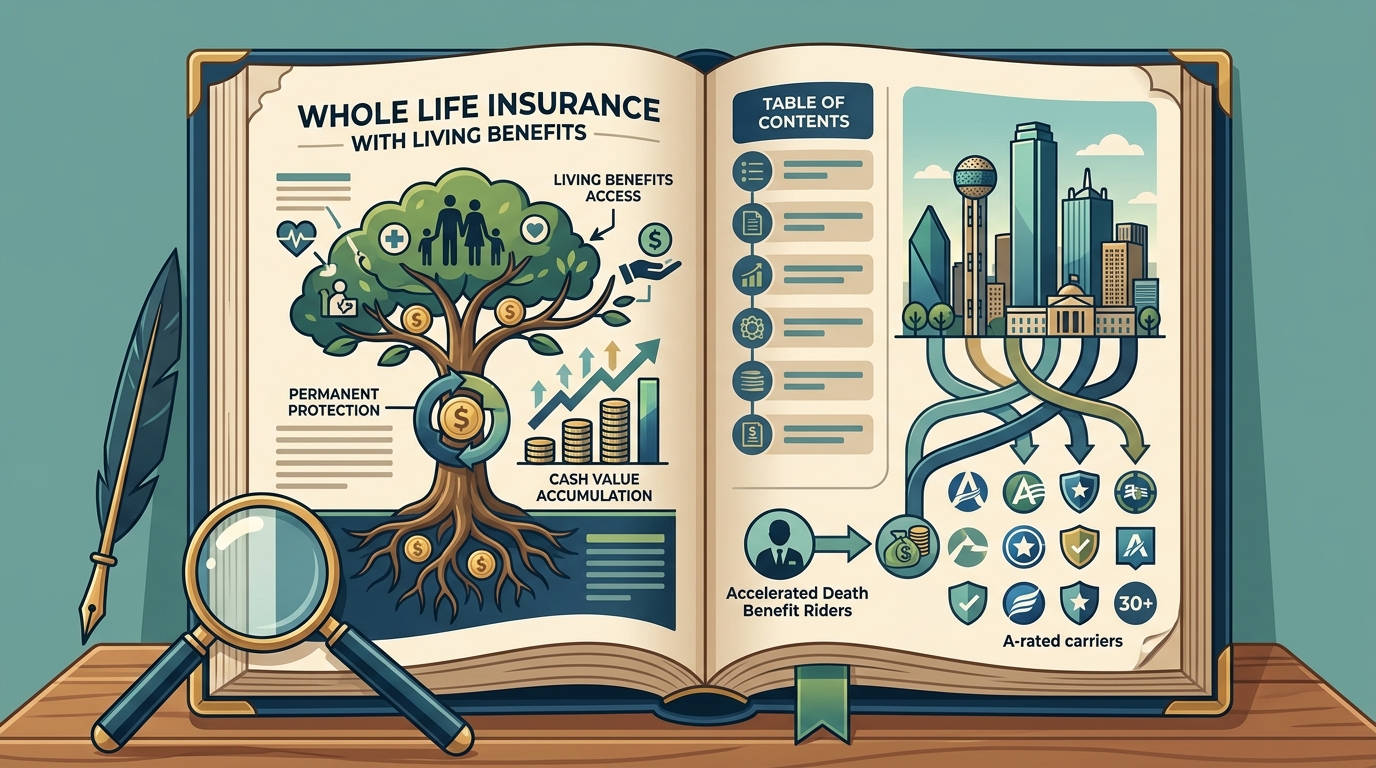
Whole life insurance with living benefits is a permanent policy that pays a death benefit and allows you to access a portion of that benefit while alive if diagnosed with a critical, chronic, or terminal illness. In Dallas, independent brokers like DG Life Group offer access to 30+ A-rated carriers that provide these riders. This guide covers how accelerated benefit riders work, how to access cash value, and how to choose the right policy for your family's financial security.
Accelerated Living Benefit Riders
Accelerated death benefit riders are optional add-ons to a life insurance policy that allow the policyholder to receive a portion of the death benefit early. This feature is often referred to as a living benefit. The primary purpose is to provide financial support during a serious health crisis, ensuring that the insured can cover medical costs or maintain their lifestyle without depleting savings.
Types of Living Benefits
Most carriers in Dallas offer three main types of accelerated benefits. Critical illness benefits are triggered by a diagnosis of a specific condition, such as cancer, heart attack, or stroke. Chronic illness benefits are available when a policyholder is unable to perform a certain number of daily living activities due to a cognitive or physical impairment. Terminal illness benefits are accessed when a physician certifies that the insured has a life expectancy of 24 months or less.
How the Acceleration Process Works
When a policyholder qualifies for a living benefit, they can request an advance of a percentage of the death benefit. The amount advanced is typically between 25% and 100% of the face amount, depending on the type of illness and the specific carrier guidelines. The accelerated amount is generally tax-free under Section 101 of the Internal Revenue Code if the policyholder meets the specific health criteria. It is important to note that once a benefit is accelerated, the remaining death benefit is reduced by the amount advanced.
DG Life Group specializes in educating clients on these options. Because the firm is an independent broker with access to 30+ A-rated carriers, they can compare how different insurers define qualifying conditions and the specific terms of their riders. This comparison is crucial because guidelines vary significantly between companies. For example, one carrier may require a specific stage of cancer, while another may cover a broader range of diagnoses.
Cash Value Access and Policy Loans
Policy Loans and Tax Implications
A policy loan allows the insured to borrow against the cash value of their policy. The loan is generally not considered taxable income as long as the policy remains in force. The policyholder must pay interest on the loan, and the interest rate is set by the insurance carrier. If the loan is not repaid, the outstanding balance is deducted from the death benefit paid to beneficiaries. If the cash value drops to zero due to unpaid loans and interest, the policy may lapse, which can have tax consequences.
Partial Surrenders and Withdrawals
Policyholders can also make partial surrenders, which involve withdrawing a portion of the cash value. Withdrawals up to the total premiums paid are generally tax-free. Amounts exceeding the premiums paid are considered taxable income. Partial surrenders reduce the cash value and, in some cases, the death benefit, depending on the policy structure. It is essential to understand the specific terms of the policy before making withdrawals to avoid unintended tax liabilities or policy lapses.
For residents in the Dallas-Fort Worth metroplex, understanding the interplay between cash value growth and living benefits is vital. DG Life Group provides free policy reviews to help clients understand their current coverage and how to optimize their cash value for future needs. This service is particularly useful for those who have held policies for several years and may not be aware of the full extent of their cash value access options.
Comparing Carriers and Coverage Options
Choosing the right carrier is as important as choosing the right policy type. In Dallas, independent brokers like DG Life Group have appointments with over 30 A-rated carriers. This access allows them to shop for the best fit based on an individual's health profile, financial goals, and specific needs for living benefits.
| Feature | Whole Life with Living Benefits | Term Life | Indexed Universal Life (IUL) |
|---|---|---|---|
| Cash Value Growth | Guaranteed, fixed rate | None | Variable, linked to market index |
| Living Benefits | Available via rider | Rarely available | Available via rider | Premium Stability | Level premiums | Level premiums | Flexible premiums | Policy Duration | Whole life | 10-30 years | Whole life |
The table above highlights the key differences between whole life, term life, and indexed universal life policies. Whole life policies offer the most stability and guaranteed cash value growth, making them a popular choice for those who want predictable financial planning. IULs offer the potential for higher growth but come with market risk. Term life is the most affordable but does not build cash value and rarely includes living benefits.
When comparing carriers, it is important to look at the financial strength ratings. A-rated carriers, as rated by AM Best, are considered to have excellent financial stability. DG Life Group only works with carriers that meet this standard, ensuring that clients are protected by financially sound institutions. Additionally, the specific terms of the living benefit rider should be reviewed carefully. Some carriers may have stricter definitions of qualifying illnesses or lower limits on the percentage of the death benefit that can be accelerated.
Key Takeaways
- Whole life insurance with living benefits provides a death benefit and the option to access funds early in case of serious illness.
- Accelerated death benefit riders are tax-free under specific conditions, providing a valuable financial safety net.
- Cash value in whole life policies grows tax-deferred and can be accessed through loans or partial surrenders.
- Independent brokers in Dallas, such as DG Life Group, offer access to 30+ A-rated carriers, allowing for comprehensive comparison.
- Policy loans are generally not taxable income if the policy remains in force, but unpaid loans reduce the death benefit.
- It is crucial to review the specific terms of living benefit riders, as guidelines vary significantly between carriers.
- Free policy reviews can help existing policyholders understand their cash value access options and optimize their coverage.
- Choosing an A-rated carrier ensures financial stability and reliable service for long-term policies.
Frequently Asked Questions
What is a living benefit in life insurance?
A living benefit is a rider that allows the policyholder to access a portion of the death benefit while alive if diagnosed with a critical, chronic, or terminal illness.
Are accelerated death benefits taxable?
Generally, no. Under Section 101 of the Internal Revenue Code, accelerated death benefits are tax-free if the policyholder meets the specific health criteria defined by the carrier.
How much of the death benefit can I access?
The amount varies by carrier and the type of illness. Typically, policyholders can access between 25% and 100% of the death benefit, depending on the severity of the condition.
Does accessing cash value affect my death benefit?
Yes. Policy loans and partial surrenders reduce the cash value and, in some cases, the death benefit. It is important to understand the specific terms of your policy.
Which carriers in Dallas offer whole life with living benefits?
Many A-rated carriers offer whole life policies with living benefit riders. DG Life Group, an independent broker in Dallas, has access to 30+ carriers and can help you compare options.
Is whole life insurance more expensive than term life?
Yes, whole life insurance is generally more expensive than term life because it provides permanent coverage and builds cash value. However, it offers more features, including living benefits.
Can I use my cash value for retirement income?
Yes, policy loans can be used to supplement retirement income. Since loans are generally not taxable, they can be a tax-efficient way to access funds.
What happens if I don't repay a policy loan?
If a policy loan is not repaid, the outstanding balance is deducted from the death benefit. If the cash value drops to zero, the policy may lapse, which can have tax consequences.
Conclusion
Whole life insurance with living benefits offers a powerful combination of protection and financial flexibility. By understanding how accelerated benefit riders and cash value access work, you can make informed decisions about your family's financial future. DG Life Group, based in Dallas, provides expert guidance and access to 30+ A-rated carriers to help you find the right policy. To discuss your options, schedule a free call with our team today.