
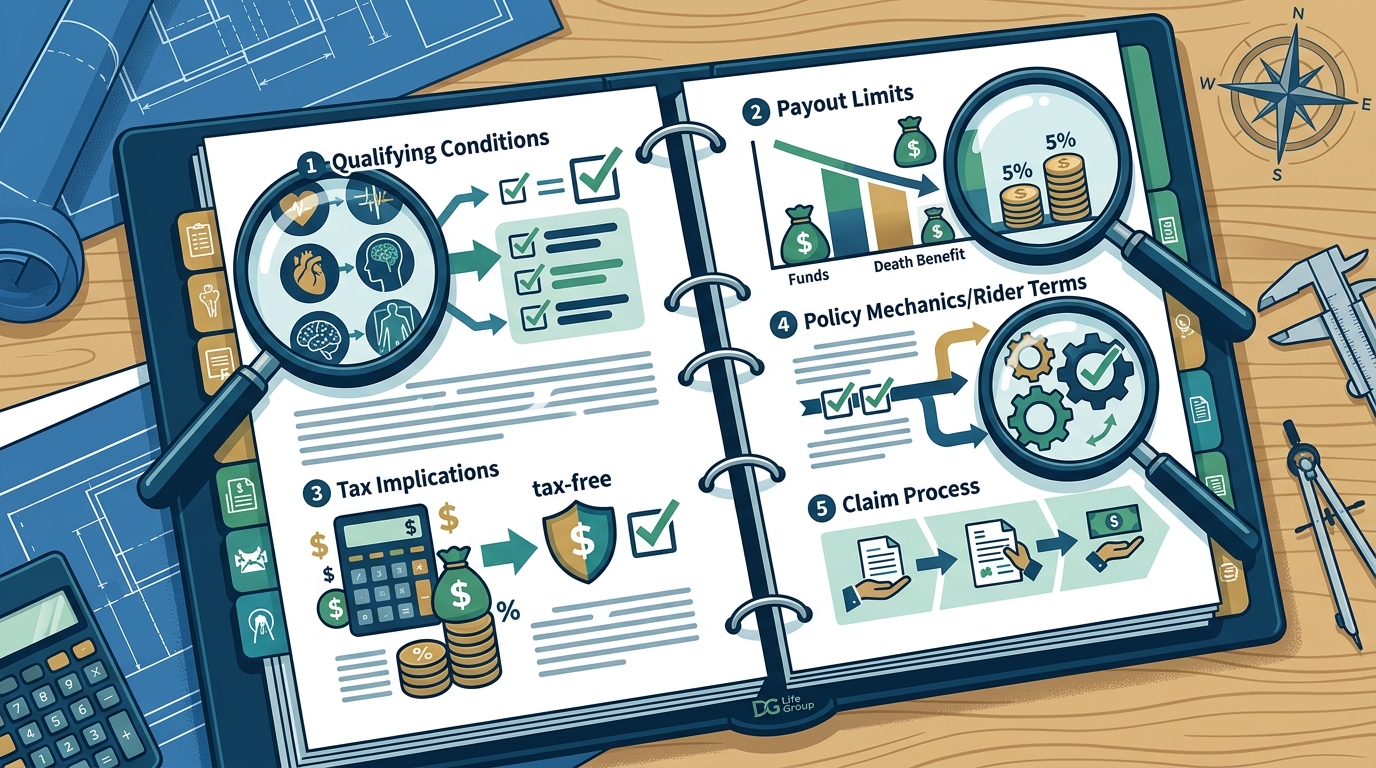
Living benefits allow policyholders to access a portion of their death benefit while alive if diagnosed with a critical, chronic, or terminal illness. Before purchasing, buyers must verify the specific qualifying conditions, payout limits, and tax implications to ensure the policy actually delivers on its promise. This guide outlines the five critical areas to investigate with your insurance provider, ensuring you understand exactly how the rider functions within your contract.
Qualifying Conditions
Living benefits are not a single, uniform product. They are typically structured as three distinct riders, each with its own definition of a qualifying event. Understanding these definitions is the first step in verifying if a policy fits your needs.
Critical Illness
Critical illness coverage is triggered by a specific, severe diagnosis. Common conditions include heart attack, stroke, and major organ transplants. However, the definition of "major" varies by carrier. Some policies require a specific medical procedure, such as a bypass surgery, while others may accept a diagnosis based on imaging or blood work. You must verify the exact list of covered conditions and the specific medical criteria required for each.
Chronic Illness
Terminal Illness
Terminal illness coverage is activated when a physician certifies that the insured has a life expectancy of 12 months or less. This is the most straightforward of the three riders but also the most restrictive. It is designed to provide immediate liquidity for end-of-life care or to settle affairs. When verifying this rider, confirm the exact timeframe required for the physician's certification, as some policies may require a prognosis of six months or less.
Benefit Payout Limits
Living benefits do not typically pay out the entire death benefit at once. Instead, they allow access to a percentage of the total coverage. Verifying these limits is crucial to understanding how much cash you can actually access during a crisis.
Percentage Caps
Most policies cap the total amount accessible under living benefits at 50% to 75% of the death benefit. Some policies may have lower caps, such as 25% or 30%. You must ask your provider for the specific percentage cap for each rider type. For example, a policy might allow up to 75% for terminal illness but only 50% for chronic illness.
Annual and Lifetime Limits
In addition to the total cap, some policies impose annual limits on how much you can withdraw in a single year. This is particularly common with chronic illness riders, which may allow smaller, recurring payments over time rather than a single lump sum. Verify whether the policy allows lump-sum payments, monthly income streams, or a combination of both. Understanding these flow-of-funds restrictions helps you plan for ongoing care costs versus one-time medical bills.
Death Benefit Reduction
Accessing living benefits reduces the death benefit payable to your beneficiaries. This is a fundamental trade-off of these riders. When you withdraw funds while alive, the remaining death benefit is reduced by the amount withdrawn, plus any associated fees or interest.
Impact on Beneficiaries
Policy Lapse Risk
In permanent life insurance policies, such as whole life or indexed universal life, cash value is used to pay premiums. If you withdraw a large portion of the cash value for living benefits, you may not have enough remaining to keep the policy in force. This can lead to a policy lapse, which may have tax consequences. Verify with your provider how living benefit withdrawals interact with your premium payment structure and cash value accumulation.
Tax Treatment
The tax implications of living benefits are a major advantage of these riders, but they are not without nuance. Generally, amounts received under a living benefits rider are excluded from federal income tax. This means you can access the funds without paying income tax on the withdrawal.
Federal Income Tax Exclusion
Under the Internal Revenue Code, proceeds from a life insurance policy are generally not taxable. Living benefits are treated as a portion of those proceeds. Therefore, if you are diagnosed with a covered condition and access funds, that money is typically tax-free. This is a significant benefit compared to other financial products, such as 401(k)s or IRAs, where withdrawals are often taxable. However, tax laws can change, and individual circumstances vary. You should consult with a tax professional to confirm how these funds will be treated in your specific situation.
State Tax Considerations
While federal tax exclusion is standard, state tax laws can differ. Some states may tax life insurance proceeds or have specific rules regarding living benefits. It is important to verify the tax treatment in your state of residence. For residents of Texas, for example, life insurance proceeds are generally not subject to state income tax, but this can vary for other states. Always confirm the local tax implications before relying on the tax-free status of these funds.
Claim Documentation Requirements
Knowing what you need to prove your claim is as important as knowing what the policy covers. Carriers require specific documentation to approve living benefit claims. Failing to provide the correct documents can delay your access to funds during a critical time.
Medical Certification
For critical and terminal illness claims, you will need a physician's certification. This document must be signed by a licensed medical doctor and must explicitly state the diagnosis and, in the case of terminal illness, the life expectancy. The policy will specify which forms the carrier accepts. Using the wrong form or missing a signature can cause significant delays. Ask your provider for the specific claim forms in advance and keep them in a safe place.
ADL Assessment for Chronic Illness
For chronic illness claims, the documentation is different. You will need to provide evidence that you are unable to perform the required number of ADLs. This may involve a physician's statement, but it often also requires a functional assessment by a nurse or other healthcare professional. The assessment must detail which ADLs you cannot perform and for how long. This process can be more complex than a simple diagnosis, so it is important to understand the specific requirements of your policy.
Key Takeaways
- Living benefits are not one-size-fits-all; they are split into critical, chronic, and terminal illness riders with distinct definitions.
- Verify the specific percentage cap on payouts, which typically ranges from 25% to 75% of the death benefit.
- Accessing living benefits permanently reduces the death benefit payable to your beneficiaries.
- Funds received under living benefits are generally excluded from federal income tax, but state laws may vary.
- Claim approval requires specific medical documentation, including physician certifications and ADL assessments.
- Withdrawals from cash value in permanent policies can affect the policy's ability to stay in force.
- Always review the policy contract to understand the exact medical criteria for each covered condition.
Frequently Asked Questions
Do all life insurance policies have living benefits?
No, living benefits are typically optional riders that you must add to your policy. They are not included in every policy by default. You must specifically request and pay for these riders when purchasing your insurance.
Can I use living benefits for any medical expense?
No, you can only use the funds if you are diagnosed with a condition that qualifies under the specific rider. For example, a minor illness would not qualify for a critical illness rider. The funds are intended for severe, qualifying conditions.
Is the money I receive from living benefits taxable?
Generally, no. Amounts received under a living benefits rider are typically excluded from federal income tax. However, you should consult a tax professional to confirm the treatment in your specific state and situation.
What happens to my death benefit if I use living benefits?
How long does it take to get a living benefit claim approved?
Approval times vary by carrier and the complexity of the claim. Simple critical illness claims may be approved in a few weeks, while chronic illness claims requiring ADL assessments can take longer. It is important to submit complete documentation to avoid delays.
Can I convert a term life policy to one with living benefits?
Some term life policies offer conversion privileges to permanent policies, which may include living benefits. However, the availability of this option depends on the specific policy and carrier. You should check your policy contract for conversion terms.
Conclusion
Verifying the details of living benefits is a critical step in protecting your family's financial future. By understanding the qualifying conditions, payout limits, and tax implications, you can make an informed decision about whether these riders are right for you. DG Life Group specializes in life insurance with living benefits, helping you navigate these complex options with access to 30+ A-rated carriers. We ensure you understand exactly what your policy covers before you sign. To plan your protection, for a free consultation.