
Living benefits riders allow policyholders to access a portion of their death benefit while still alive if diagnosed with a terminal, critical, or chronic illness. Before purchasing, buyers must verify the specific waiting periods, payout percentages, and tax implications attached to these riders. This guide details the critical factors to check, including how waiting periods affect eligibility and how DG Life Group helps navigate these complex policy features.
Waiting Periods and Eligibility
Waiting periods are the most critical technical detail in a living benefits rider. A waiting period is a mandatory timeframe that must elapse after a qualifying diagnosis before the policyholder can access funds. For terminal illness riders, this period is often short, ranging from 30 to 90 days. However, for chronic or long-term care riders, the waiting period can extend to several months or even years, depending on the carrier's underwriting guidelines.
Terminal vs. Chronic Waiting Periods
Terminal illness riders typically require a physician's certification that the insured has 12 months or less to live. The waiting period here is designed to prevent fraud and ensure the diagnosis is confirmed. In contrast, chronic illness riders often require the insured to be substantially limited in performing activities of daily living for a specific duration, such as 90 consecutive days. Buyers must verify if the waiting period resets if the condition improves and then worsens again.
Impact on Premiums
Adding a living benefits rider usually increases the base premium. The cost depends on the type of rider and the coverage amount. At DG Life Group, we compare riders across 30+ A-rated carriers to ensure the premium increase is justified by the breadth of the benefits. Some carriers offer these riders at no additional cost, while others charge a significant premium load. Verifying the exact cost impact is essential before finalizing a policy.
Payout Structure and Death Benefit Reduction
Percentage Limits
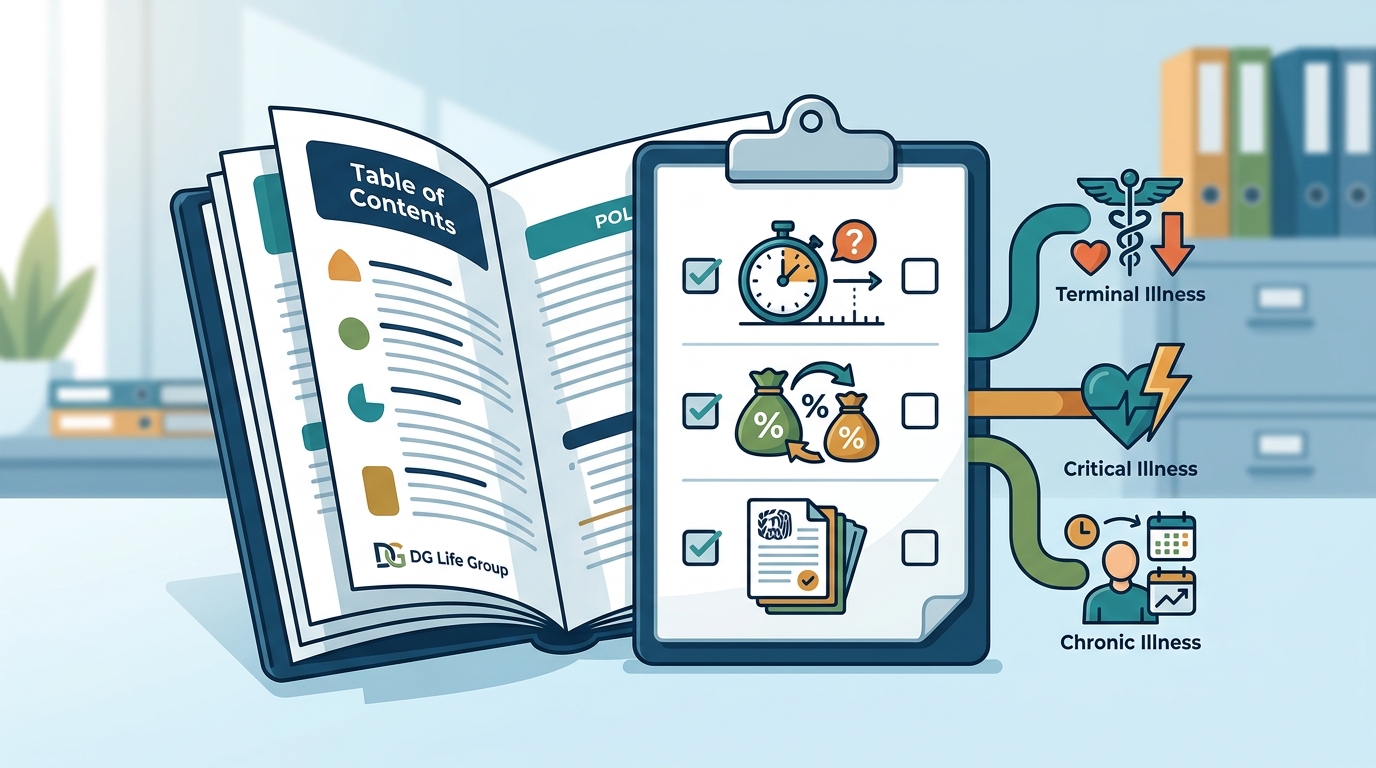
Most carriers cap the total amount that can be accessed via living benefits. A common limit is 75% of the death benefit for terminal illness and a lower percentage, such as 50% or 60%, for chronic or long-term care. Buyers must verify these caps to ensure the remaining death benefit is sufficient to cover their estate or family's needs. If the cap is too low, the rider may not provide adequate financial protection.
Payment Frequency
Some riders allow a lump-sum payout, while others require monthly or quarterly payments. Lump-sum payouts are often preferred for critical illnesses where immediate, large expenses are incurred. Monthly payments are more common for long-term care riders, aligning with the ongoing cost of care. The choice between lump-sum and periodic payments can affect the total amount received due to the reduction in the death benefit over time.
Tax Implications and IRS Rules
Life insurance death benefits are generally income-tax-free. However, living benefits payouts are treated differently by the IRS. Payouts for terminal illness are typically income-tax-free. Payouts for chronic illness are also generally income-tax-free if the funds are used for qualified long-term care expenses or if the insured is certified as chronically ill. Critical illness payouts, however, may be taxable if the policy is not structured correctly or if the funds are not used for specific medical expenses.
Qualified Expenses
To maintain tax-free status for chronic illness payouts, the funds often must be used for qualified long-term care services. These include in-home care, assisted living, and nursing home care. Buyers should verify with their tax advisor how the specific rider's payout structure aligns with IRS Section 101(g). Misunderstanding these rules can lead to unexpected tax liabilities.
State-Specific Rules
While federal tax rules apply nationwide, some states have their own regulations regarding life insurance payouts. Texas, for instance, has specific creditor protection laws that shield life insurance proceeds. Buyers in Texas should verify how their state treats living benefits payouts, especially if they have significant debts or legal liabilities. DG Life Group provides guidance on these state-specific nuances for clients in Dallas and across the DFW metroplex.
Carrier-Specific Definitions and Exclusions
Not all carriers define illnesses the same way. A condition that qualifies as "critical" under one carrier's guidelines may not qualify under another. Buyers must verify the specific definitions of terminal, critical, and chronic illnesses in the policy contract. This includes understanding which conditions are excluded, such as pre-existing conditions or illnesses diagnosed before the policy's effective date.
Pre-Existing Condition Exclusions
Most carriers have a pre-existing condition exclusion period, often ranging from 1 to 3 years. If a condition is diagnosed during this period, it may not qualify for living benefits. Buyers with known health issues should verify this exclusion period carefully. At DG Life Group, we help clients select carriers with guidelines that best fit their specific health history.
Documentation Requirements
Accessing living benefits requires medical documentation. Buyers should verify what level of documentation is needed. Some carriers require a simple physician's statement, while others demand detailed medical records and specialist certifications. Understanding these requirements in advance can prevent delays in accessing funds when they are needed most.
Comparison of Living Benefits Riders
| Rider Type | Typical Waiting Period | Max Payout % | Tax Status | Common Use Case |
|---|---|---|---|---|
| Terminal Illness | 30-90 days | 75-100% | Income-Tax-Free | End-of-life expenses |
| Critical Illness | Varies by condition | 50-75% | May be Taxable | Medical bills, lost income |
| Chronic Illness | 90 days+ | 50-75% | Income-Tax-Free (if qualified) | Long-term care costs |
Key Takeaways
- Verify the waiting period for each type of living benefit rider, as it varies significantly between terminal, critical, and chronic illnesses.
- Understand that living benefits reduce the death benefit permanently; check the maximum payout percentage to ensure sufficient coverage remains for beneficiaries.
- Confirm the tax implications of payouts, as terminal and chronic illness payouts are generally tax-free, while critical illness payouts may be taxable.
- Review carrier-specific definitions of illnesses, including exclusions for pre-existing conditions and documentation requirements.
- Compare riders across multiple carriers, as guidelines and costs vary widely even among A-rated companies.
- Consult with a tax advisor to ensure the policy structure aligns with IRS rules and state-specific regulations.
- Work with an independent broker like DG Life Group to access a broader range of carrier options and tailored advice.
Frequently Asked Questions
Do living benefits riders cost extra?
Yes, most living benefits riders increase the base premium. The cost depends on the type of rider and the coverage amount. Some carriers offer basic riders at no additional cost, but comprehensive riders usually carry a premium load. It is essential to compare the cost of the rider against the potential benefits it provides.
Can I access living benefits more than once?
Generally, no. Most riders allow only one payout event per type of illness. For example, if you access funds for a critical illness, you cannot access them again for the same condition. However, you may be able to access funds for a different type of illness, such as a chronic condition, if the policy allows it and the death benefit has not been fully exhausted.
What happens to the death benefit after a payout?
Are living benefits payouts taxable?
Payouts for terminal and chronic illnesses are generally income-tax-free. Payouts for critical illnesses may be taxable if the funds are not used for qualified medical expenses. Buyers should consult with a tax advisor to understand the specific tax implications of their policy.
How long does it take to receive living benefits?
The timeline depends on the carrier and the type of rider. Terminal illness payouts are often processed within 30 to 60 days after documentation is submitted. Chronic illness payouts may take longer due to the waiting period and documentation requirements. Buyers should verify the carrier's processing times before purchasing.
Can I add a living benefits rider to an existing policy?
In some cases, yes. However, adding a rider to an existing policy may require new underwriting and can increase the premium. It is often more cost-effective to purchase a new policy with the desired riders if the existing policy does not include them. Consult with your broker to determine the best option for your situation.
What is the difference between a living benefits rider and a separate critical illness policy?
A living benefits rider is attached to a life insurance policy and reduces the death benefit when accessed. A separate critical illness policy is a standalone product that pays a lump sum upon diagnosis and does not affect any life insurance death benefit. The choice between the two depends on your financial goals and existing coverage.
How does DG Life Group help with living benefits?
DG Life Group is an independent broker with access to 30+ A-rated carriers. We help clients compare living benefits riders across multiple carriers to find the best fit for their health history and financial needs. Our team provides detailed guidance on waiting periods, payout structures, and tax implications to ensure informed decision-making.
Conclusion
Verifying the details of living benefits riders is essential for anyone seeking comprehensive financial protection. By understanding waiting periods, payout structures, tax implications, and carrier-specific definitions, buyers can make informed decisions that align with their long-term goals. DG Life Group provides the expertise and carrier access needed to navigate these complexities, ensuring that your policy offers the protection you need while you are alive and after you are gone. To discuss your options, schedule a call with our team today.